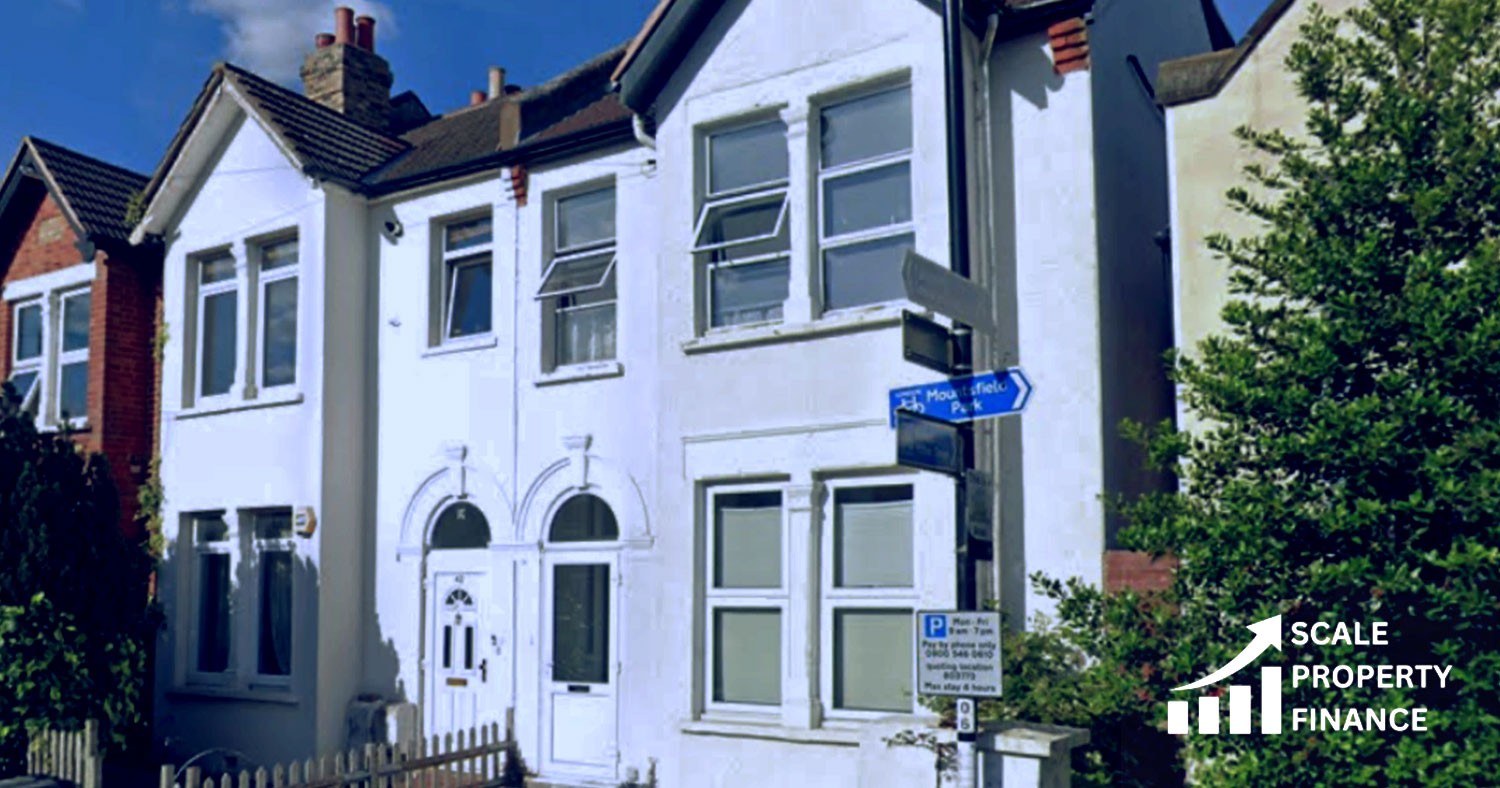
A recent completion for a repeat client, two HMO mortgages placed and drawn on the same day, moving both properties off bridging finance and onto long-term HMO products.
On well-let HMOs, the strongest outcome often comes through a yield-based valuation, where the property is valued on the rental income it generates rather than on standard residential comparables. On these two files, that approach produced a materially stronger valuation than bricks-and-mortar would have, feeding directly into the capital available to the client.
HMOs sit within a specialist segment of the mortgage market. Knowing which lenders will accept a yield-based valuation on a particular property type, and how to structure the file around that approach, makes a real difference to the result.
If you have an HMO or MUFB portfolio you’d like to refinance, or if you want to understand whether a yield-based valuation applies to your asset, get in touch.
hello@scalepropertyfinance.co.uk
0117 427 4568